Published on September 11, 2026
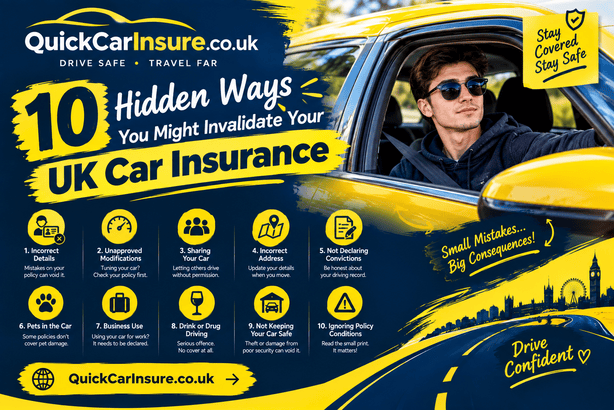
10 Hidden Ways You Might Invalidate Your UK Car Insurance
Driving without valid car insurance on public roads is illegal in Great Britain. While most drivers pay their premiums regularly and assume they are fully covered, simple mistakes, minor oversights, or lifestyle changes can completely void an active policy without you realizing it.
If your policy becomes invalid, your insurer can refuse to pay out for claims, leaving you personally liable for costly repairs, legal fees, and third-party damages. Furthermore, the police can treat an invalid policy as driving completely uninsured, resulting in 6 penalty points, a £300 fixed fine, and vehicle impoundment.
Common Reasons Car Insurance Policies Become Invalid
+------------------------------------------------------------------------------------------------+
|                             KEY CAUSES OF CAR INSURANCE INVALIDATION                           |
+--------------------------+-------------------------------+-------------------------------------+
| Invalidation Reason      | Common Mistake Made           | Legal & Financial Consequence       |
+--------------------------+-------------------------------+-------------------------------------+
| Incorrect Personal Details| Outdated address or job title | Claim rejection; cancellation fee   |
| Undeclared Modifications | Window tints, remaps, alloys  | Complete policy voidance            |
| "Fronting" Fraud         | Parent claims as main driver  | Criminal charge; total claim denial |
| Incorrect Class of Use   | Driving for work without cover| Uninsured driving penalties         |
| Vehicle Insecurity       | Leaving car unlocked/defrosting| Stolen vehicle claim rejected       |
+--------------------------+-------------------------------+-------------------------------------+
1. Providing an Outdated or Incorrect Address
Insurers calculate risk based on local crime rates, traffic density, and off-street parking availability. If you move house or register your vehicle at a parent's address to secure lower premiums, your insurer can declare the policy void due to misrepresentation.
2. Undeclared Vehicle Modifications
Any physical or performance change to your vehicle must be declared to your insurer. This includes cosmetic upgrades like alloy wheels, window tinting, exhaust changes, body wraps, or engine remapping. Failing to inform your provider—even for minor cosmetic changes—can invalidate a claim.
3. Insurance "Fronting" (Lying About the Main Driver)
Fronting occurs when a higher-risk driver (such as a 17-year-old learner or newly qualified driver) is listed as a named driver, while a lower-risk parent is falsely declared as the main driver. Fronting is illegal insurance fraud; it automatically invalidates the policy and can lead to criminal prosecution.
4. Failing to Update Your Job Title or Industry
Insurers use occupation categories to evaluate road risk. Moving into a new job role or changing industries without informing your insurer can render your policy invalid during a claim investigation.
5. Driving for Business Without the Correct Class of Use
Standard social, domestic, and commuting (SD&P) policies do not cover business-related travel, such as visiting client sites, travelling between multiple work locations, or making deliveries. If you use your car for work purposes outside standard commuting, you must have dedicated business use cover.
6. Charging Passengers for Lifts for Profit
Car-sharing is allowed if passengers only contribute toward actual fuel costs. However, if you charge passengers higher rates to make a profit, your policy becomes void unless you hold a licensed private hire or taxi permit.
7. Leaving Your Car Unlocked or Running While Defrosting
Insurers enforce "keys in or on vehicle" exclusion clauses. If you leave your car running unattended on your driveway during cold winter mornings to defrost the windscreen and it is stolen, your insurer will refuse the claim due to negligence.
8. Overloading Your Vehicle Beyond Legal Limits
Exceeding your vehicle’s Maximum Authorised Mass (MAM) with heavy luggage, equipment, or too many passengers compromises vehicle handling and braking distances, invalidating your policy in an accident.
9. Omitting Past Motoring Convictions or Penalty Points
Failing to declare unspent driving convictions, speeding points, or previous accidents when applying for cover constitutes breach of contract. Insurers regularly cross-check details with the DVLA database.
10. Undeclared Medical Conditions
If you develop a medical condition that must be declared to the DVLA (such as severe visual impairments, epilepsy, or diabetes), you must also notify your insurer. Unreported conditions can leave you personally responsible for collision costs.
Avoid Policy Risks with QuickCarInsure.co.uk
Navigating complex policy adjustments or adding short-term business cover to an existing annual plan can be difficult. Standalone temporary car insurance from QuickCarInsure.co.uk provides a clean, flexible solution for borrowing vehicles or adding extra drivers without messing up your primary policy.
Key benefits of short-term cover through QuickCarInsure.co.uk:
-
Standalone Protection: Any claim made under a temporary policy stays separate, keeping the vehicle owner's No Claims Discount (NCD) 100% protected.
-
Flexible Durations: Choose exact cover windows ranging from 1 hour up to 28 days.
-
Instant Digital Setup: Complete your quote online in under two minutes with instant policy documentation sent to your email.
-
Direct MID Database Uploads: Active policies upload straight to the Motor Insurance Database (MID) for immediate legal road use.
Frequently Asked Questions
Can my insurance be cancelled if I forget to change my address?
Yes. Insurers evaluate risk based on your permanent residential postcode. Failing to update your address can lead to rejected claims or policy cancellation.
Does temporary car insurance cover business use?
Short-term policies arranged through QuickCarInsure.co.uk offer clear options for business travel, ensuring you stay fully legal when visiting client sites or travelling for work.
Will borrowing a car with temporary insurance impact the owner's NCD?
No. Temporary cover operates as an independent policy. If an incident occurs, the claim is handled entirely through the short-term policy, leaving the owner's annual policy and NCD untouched.
Need flexible, hassle-free cover today? Visit QuickCarInsure.co.uk to secure fully comprehensive temporary car insurance in under two minutes!